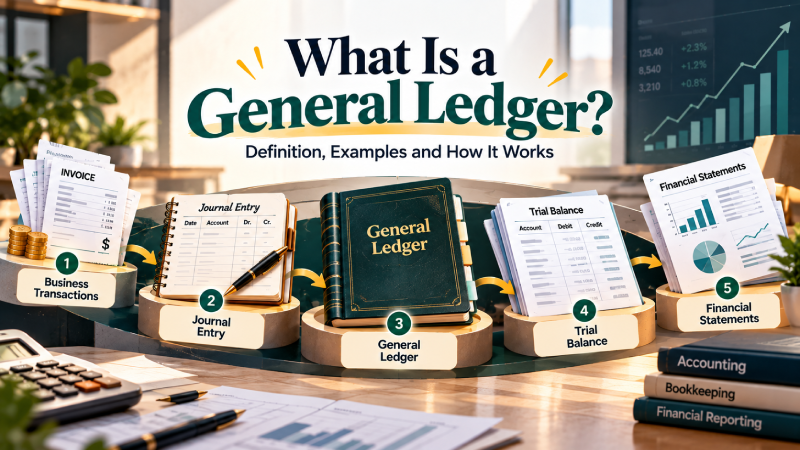
A general ledger is the central accounting record used to organize a business’s financial transactions by account. It brings together the debits, credits, and balances for accounts such as cash, accounts receivable, accounts payable, revenue, expenses, assets, liabilities, and equity.
In a double entry accounting system, transactions are first recorded through journal entries and then posted to the appropriate general ledger accounts. The balances in the general ledger are later used to prepare a trial balance and financial statements.
For small businesses, the general ledger provides a structured way to understand where money comes from, where it goes, what the business owns, and what it owes.
Key Highlights
- A general ledger is the central record of a business’s financial transactions organized by account.
- It contains accounts such as assets, liabilities, equity, revenue, and expenses.
- Journal entries are posted to the appropriate general ledger accounts.
- The general ledger provides the account balances used to prepare a trial balance.
- General ledger information also supports financial statements such as the balance sheet and income statement.
- A general ledger is different from a journal because the journal records transactions chronologically while the ledger organizes them by account.
- Accounting software can automatically update ledger accounts when transactions are recorded.
- A balanced general ledger does not automatically mean every transaction has been recorded or classified correctly.
What Is a General Ledger?
A general ledger is the main accounting record that organizes a business’s financial transactions by individual accounts.
Instead of viewing transactions only in chronological order, the general ledger groups them according to the account they affect.
For example, a business may have separate ledger accounts for:
- Cash
- Accounts receivable
- Inventory
- Equipment
- Accounts payable
- Loans payable
- Owner’s equity
- Sales revenue
- Rent expense
- Advertising expense
Each account records the transactions that affect its balance.
This makes it easier for a business owner, bookkeeper, or accountant to understand the financial activity of the business and prepare financial reports.
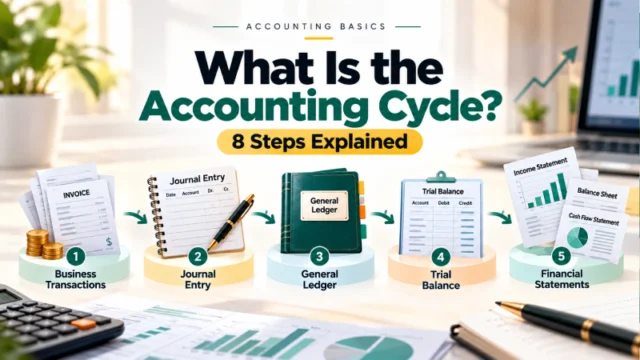
The general ledger is therefore an important part of the broader accounting cycle, which moves financial information from transactions through recording, adjustment, reporting, and closing.
Also Read: What Is the Accounting Cycle? 8 Steps Explained
How Does a General Ledger Work?
The general ledger works as part of the double entry accounting process.
A simplified flow looks like this:
Business transaction → Journal entry → General ledger → Trial balance → Financial statements
For example, suppose a small business pays $500 for office supplies using its bank account.
The journal entry could be:
| Account | Debit | Credit |
|---|---|---|
| Office Supplies Expense | $500 | |
| Cash | $500 |
The transaction is then posted to the appropriate general ledger accounts.
The Office Supplies Expense account receives a $500 debit.
The Cash account receives a $500 credit.
This allows the business to see how the transaction changed individual account balances.
After many transactions have been recorded, the balances of these accounts can be summarized in a trial balance.
What Information Does a General Ledger Contain?
The exact format can vary depending on the accounting system, but a general ledger commonly contains information such as:
- Account name
- Account number or GL code
- Transaction date
- Transaction description
- Reference number
- Debit amount
- Credit amount
- Running balance
A simple ledger account might look like this:
| Date | Description | Debit | Credit | Balance |
|---|---|---|---|---|
| Jan. 1 | Owner investment | $5,000 | $5,000 | |
| Jan. 3 | Office supplies | $500 | $4,500 | |
| Jan. 5 | Customer payment | $1,500 | $6,000 |
This example shows how transactions can change the balance of an account over time.
Modern accounting software usually maintains this information electronically instead of using a physical ledger book.
Five Main Types of General Ledger Accounts
General ledger accounts are commonly organized into five major categories:
- Assets
- Liabilities
- Equity
- Revenue
- Expenses
These categories are closely connected to the accounting equation and financial statements.
1. Asset Accounts
Assets are resources owned or controlled by a business that have economic value.
Examples include:
- Cash
- Accounts receivable
- Inventory
- Equipment
- Vehicles
- Buildings
- Computers
For example, if a business purchases a $2,000 computer for business use, the equipment account records the transaction as an asset.
2. Liability Accounts
Liabilities represent amounts a business owes to other parties.
Examples include:
- Accounts payable
- Business loans
- Credit card balances
- Payroll liabilities
- Taxes payable
If a company takes out a $20,000 business loan, the loan payable account records the liability.
3. Equity Accounts
Equity represents the owner’s or shareholders’ interest in the business after liabilities are considered.
Examples include:
- Owner’s capital
- Common stock
- Additional paid in capital
- Retained earnings
- Owner’s drawings or distributions
The exact equity accounts depend on the business structure.
4. Revenue Accounts
Revenue accounts record income earned from selling products or providing services.
Examples include:
- Sales revenue
- Service revenue
- Consulting revenue
- Subscription revenue
Revenue is generally reported on the income statement.
5. Expense Accounts
Expense accounts record costs associated with operating the business.
Examples include:
- Rent
- Advertising
- Insurance
- Utilities
- Salaries
- Office supplies
- Software subscriptions
Expenses are generally reported on the income statement and reduce profit.
General Ledger Example for a Small Business
Consider a small web design business.
During January, the business has these transactions:
Transaction 1: Owner invests $10,000
The business receives $10,000 in cash from the owner.
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,000 | |
| Owner’s Equity | $10,000 |
Transaction 2: Business pays $1,000 for software and office expenses
| Account | Debit | Credit |
|---|---|---|
| Software and Office Expense | $1,000 | |
| Cash | $1,000 |
Transaction 3: Business earns $3,000 from a client
Assume the client pays immediately.
| Account | Debit | Credit |
|---|---|---|
| Cash | $3,000 | |
| Service Revenue | $3,000 |
The related ledger balances would now reflect:
| Account | Debit Activity | Credit Activity |
|---|---|---|
| Cash | $13,000 | $1,000 |
| Software and Office Expense | $1,000 | |
| Service Revenue | $3,000 | |
| Owner’s Equity | $10,000 |
The ending cash balance from these three transactions would be:
$10,000 − $1,000 + $3,000 = $12,000
The example demonstrates how individual transactions flow into separate accounts in the general ledger.
General Ledger vs General Journal
The general ledger and general journal are closely related, but they serve different purposes.
| General Journal | General Ledger |
|---|---|
| Records transactions chronologically | Organizes transactions by account |
| Shows individual journal entries | Shows activity within each account |
| Usually records transactions first | Receives transactions posted from journals |
| Focuses on transaction sequence | Focuses on account balances |
| Helps document the original entry | Helps summarize account activity |
For example, a sale may first be recorded in the journal.
The related amounts are then posted to accounts such as Sales Revenue, Cash, or Accounts Receivable in the general ledger.
So the simple relationship is:
Journal = chronological record
General ledger = account based record
Trial balance = summary of ledger balances
This distinction is an important part of understanding the accounting cycle.
General Ledger vs Trial Balance
A general ledger is not the same as a trial balance.
The general ledger contains the detailed transaction activity within individual accounts.
A trial balance summarizes the ending balances of the general ledger accounts at a specific point in time and checks whether total debits equal total credits.
For example:
| General Ledger | Trial Balance |
|---|---|
| Contains account transaction details | Summarizes account balances |
| Organized by account | Lists accounts and their ending balances |
| Used throughout the accounting process | Used as an accounting accuracy check |
| Provides information for the trial balance | Uses balances from the general ledger |
A trial balance therefore depends on the account balances maintained in the general ledger.
General Ledger vs Balance Sheet
The general ledger is also different from the balance sheet.
A general ledger contains detailed activity for many types of accounts.
A balance sheet is a financial statement that reports:
- Assets
- Liabilities
- Equity
at a specific point in time.
The balance sheet uses information from relevant general ledger accounts.
For example, the Cash ledger account may contain hundreds of transactions during a month, while the balance sheet may simply report the ending cash balance.
General Ledger vs Income Statement
An income statement reports revenue, expenses, gains, and losses for a particular reporting period.
The general ledger contains the detailed account activity that supports those figures.
For example:
General Ledger
Advertising Expense:
- January 5: $300
- January 12: $200
- January 25: $500
Total Advertising Expense: $1,000
The income statement may then report:
Advertising Expense: $1,000
The ledger provides the underlying accounting detail behind the reported amount.
What Is a GL Code?
A GL code, or general ledger code, is an identifier assigned to an accounting account.
Businesses may use codes to organize their chart of accounts.
For example:
| GL Code | Account |
|---|---|
| 1000 | Cash |
| 1100 | Accounts Receivable |
| 1200 | Inventory |
| 2000 | Accounts Payable |
| 3000 | Owner’s Equity |
| 4000 | Sales Revenue |
| 5000 | Operating Expenses |
The numbering system can vary between businesses and accounting software.
GL codes help bookkeepers and accountants classify transactions consistently.
The roles of bookkeeping and accounting are closely connected here: bookkeeping helps maintain transaction records, while accounting uses those records for reporting and analysis.
What Is a Chart of Accounts?
A chart of accounts is a structured list of the accounts a business uses to record its financial transactions.
For example, a small business chart of accounts might include:
Assets
- Cash
- Accounts Receivable
- Equipment
Liabilities
- Accounts Payable
- Loan Payable
Equity
- Owner’s Capital
Revenue
- Service Revenue
- Product Sales
Expenses
- Rent
- Advertising
- Insurance
- Software
The chart of accounts provides the structure used to organize the accounts that appear in the general ledger.
In simple terms:
Chart of accounts = list of accounts
General ledger = transaction activity within those accounts
How the General Ledger Fits Into the Accounting Cycle
The general ledger is one stage of the accounting cycle.
A simplified process is:
1. Identify Transactions
The business identifies financial transactions such as sales, purchases, payments, and expenses.
2. Record Journal Entries
The transactions are recorded using debits and credits.
3. Post to the General Ledger
The journal entry amounts are posted to the appropriate ledger accounts.
4. Prepare a Trial Balance
The ending balances from the general ledger are used to prepare the trial balance.
5. Record Adjusting Entries
Adjustments may be recorded for items such as accrued expenses, prepaid expenses, depreciation, and other period end accounting requirements.
6. Prepare Financial Statements
Adjusted account balances are used to prepare financial statements.
7. Close Temporary Accounts
Revenue and expense accounts are closed at the end of the accounting period as part of the closing process.
This is why the general ledger plays a central role in turning individual transactions into financial information.
Why Is a General Ledger Important?
A properly maintained general ledger helps businesses:
General ledger balances provide the underlying information used to prepare financial reports.
Understanding what accounting is helps explain how information from the general ledger is ultimately used to organize, summarize, and report financial activity.
Track Financial Activity
It provides an organized record of financial transactions by account.
Prepare Financial Statements
General ledger balances provide the underlying information used to prepare financial reports.
Identify Accounting Errors
Reviewing ledger activity can help identify unusual amounts, duplicate transactions, missing entries, or incorrect classifications.
Understand Account Balances
Business owners can review individual accounts to understand where money is being earned or spent.
Support Reconciliation
Ledger balances can be compared with bank statements, invoices, receipts, and other records during reconciliation.
Support Tax and Financial Reporting
Accurate accounting records provide supporting information for financial reporting and tax preparation.
The IRS states that businesses generally need records that support items of income, deductions, and credits reported on tax returns. Businesses should therefore maintain appropriate records for their circumstances.
Common General Ledger Mistakes
Even with a structured accounting system, errors can occur.
Recording a Transaction in the Wrong Account
For example, a business may record equipment as an ordinary office expense when the transaction should be classified as an asset under the applicable accounting treatment.
Entering the Wrong Amount
A $1,000 transaction entered as $10,000 can significantly affect account balances.
Missing Transactions
If a transaction is never recorded, the general ledger will not contain it.
Duplicate Transactions
Recording the same transaction twice can overstate revenue, expenses, assets, or liabilities.
Incorrect Debit or Credit
Posting an amount to the wrong side of an account can cause account balances and trial balance totals to be incorrect.
Poor Reconciliation
A business that does not regularly reconcile its records may allow errors to remain undiscovered for longer.
Can Accounting Software Manage a General Ledger?
Yes.
Modern accounting software can automatically update general ledger accounts when transactions are recorded.
For example, when a business records a customer payment, accounting software may automatically update the relevant cash or bank account and the corresponding revenue or accounts receivable account.
This reduces manual data entry and can make reporting more efficient.
However, automation does not eliminate the need for review.
Businesses still need to:
- Review account classifications
- Reconcile accounts
- Check unusual transactions
- Review financial reports
- Correct errors
- Maintain supporting documentation
Accounting software automates many accounting processes, but accurate financial information still depends on appropriate setup and review.
How Often Should a General Ledger Be Reviewed?
There is no single schedule that applies to every business.
Many businesses review their accounting records regularly as part of their monthly, quarterly, or annual close process.
The appropriate frequency can depend on:
- Business size
- Transaction volume
- Industry
- Internal controls
- Reporting requirements
- Tax requirements
- Management needs
Businesses with frequent transactions may benefit from more regular review.
General Ledger for Small Businesses
Small businesses may have a relatively simple general ledger compared with large organizations.
A small business might maintain accounts for:
- Checking account
- Savings account
- Accounts receivable
- Equipment
- Accounts payable
- Business loans
- Owner’s equity
- Sales
- Rent
- Advertising
- Payroll
- Software
- Utilities
The number of accounts should reflect the business’s reporting and record keeping needs.
A more complicated chart of accounts is not automatically better.
The goal is to organize financial information clearly and consistently.
Frequently Asked Questions
What is a general ledger?
A general ledger is the central accounting record that organizes a business’s financial transactions by account. It contains account activity and balances that support the preparation of a trial balance and financial statements.
What is the purpose of a general ledger?
The general ledger organizes financial transactions by account, helps track account balances, supports financial reporting, and provides detailed records for reviewing and reconciling business transactions.
What are the five main general ledger accounts?
The five broad account categories are assets, liabilities, equity, revenue, and expenses.
What is the difference between a journal and a general ledger?
A journal records transactions in chronological order, while a general ledger organizes those transactions by account.
What is the difference between a general ledger and a trial balance?
The general ledger contains detailed account activity, while the trial balance summarizes account balances at a specific point in time and checks whether total debits equal total credits.
Is a general ledger the same as a balance sheet?
No. A general ledger contains detailed transaction activity across many accounts. A balance sheet is a financial statement that reports assets, liabilities, and equity at a specific date.
What is a GL code?
A GL code is an account identifier used to organize transactions within the general ledger.
What is a chart of accounts?
A chart of accounts is a structured list of the accounts a business uses to classify and record its financial transactions.
Can accounting software create a general ledger?
Yes. Most modern accounting software can automatically maintain general ledger accounts as transactions are entered and categorized.
How often should a general ledger be reviewed?
Businesses may review their general ledger as part of regular monthly, quarterly, or annual accounting processes. The appropriate frequency depends on the business’s transaction volume and reporting needs.
Does every business need a general ledger?
Businesses using a formal accounting system generally need organized records of their financial transactions. The exact accounting system and level of detail can vary based on business structure, size, transaction volume, and reporting requirements.
What happens after the general ledger?
The account balances in the general ledger are used to prepare a trial balance. After necessary adjustments, the adjusted balances support the preparation of financial statements.
Final Thoughts
The general ledger is one of the most important components of an accounting system because it organizes financial activity into individual accounts.
While a journal records transactions chronologically, the general ledger shows how those transactions affect specific accounts. Those account balances then become the foundation for the trial balance and, after appropriate adjustments, financial statements.
For a small business, understanding the general ledger can make accounting reports easier to understand and help explain where financial numbers come from.
The key relationship is simple:
Transactions → Journal Entries → General Ledger → Trial Balance → Financial Statements
Understanding this flow makes it easier to understand the wider accounting process and how individual transactions eventually become useful financial information.